A perpetual inventory system updates the inventory account every time stock is received or sold, so the books show what should be on the shelf and what each sale cost. A physical count still has to confirm the records. Which cost method you may use, FIFO, weighted average or LIFO, depends on the accounting standard you report under.
What is a perpetual inventory system?
It is an inventory management method in which the Inventory account is updated at the time of each purchase and sale, not once at the end of the period.
Every sale is recorded twice. One entry books the revenue. A second moves the cost of the goods from Inventory to Cost of Goods Sold, so gross margin is current at any moment. OpenStax’s accounting textbook describes the same two-entry pattern and notes that the adjustments left at period end are typically for shrinkage.
Updating is normally done by scanning. OpenStax says it is usually accomplished with auto-ID technology, “such as optical-scan barcode or radio frequency identification” labels. Two typical setups are a shop scanning each sale and a warehouse scanning each pallet in and out.
How does a perpetual inventory system work?
Four steps repeat for every item: track the movement, record the entry, reorder from the data, and count to reconcile.

- Track. Scan each receipt and each sale, so every movement leaves a record.
- Record. Each movement updates the item’s quantity and cost and posts to the ledger. The next section shows the entries.
- Reorder. The system compares stock on hand with the reorder point and flags what to buy. Work out yours with our reorder point calculator.
- Count and reconcile. A count compares the shelf with the records, and the difference is booked as shrinkage. Records do not replace counting, as the section on physical counts below explains.
What do the journal entries look like?
Every receipt and sale posts a debit and a credit at the moment it happens.
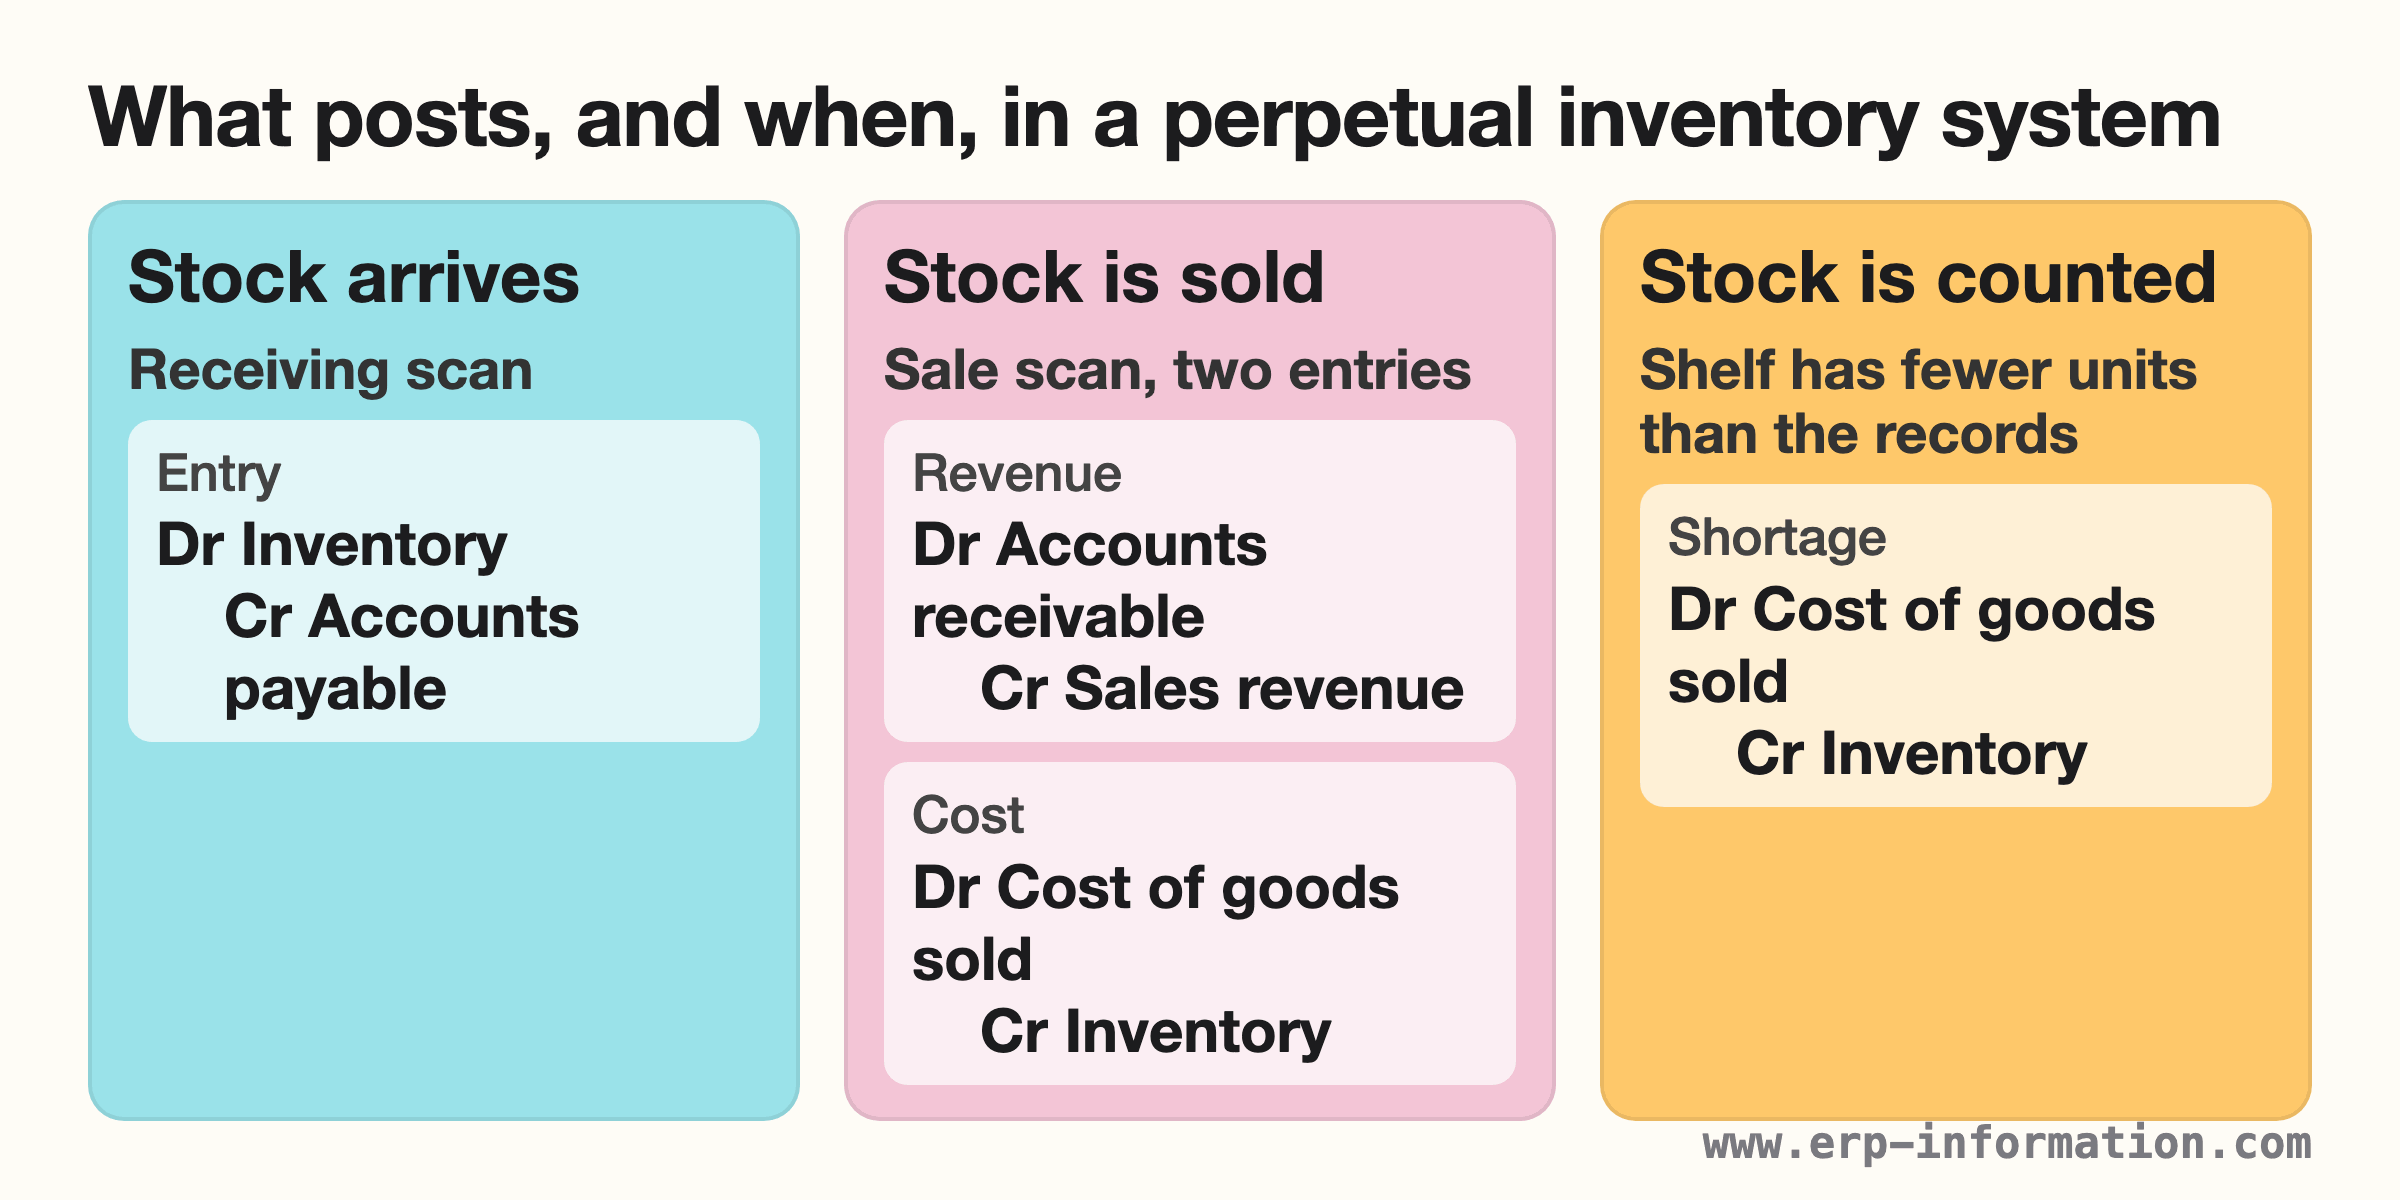
The example uses one product and the FIFO cost method. Opening stock is 100 units at $10. Purchases and sales are on credit, each sale is at $25 a unit, and a count is taken on January 31. All figures are our calculation.
| Date and event | Debit | Credit | Amount |
|---|---|---|---|
| Jan 10, buy 100 at $12 | Inventory | Accounts payable | $1,200 |
| Jan 15, sell 120 at $25 | Accounts receivable | Sales revenue | $3,000 |
| Jan 15, cost of that sale | Cost of goods sold | Inventory | $1,240 |
| Jan 20, buy 100 at $14 | Inventory | Accounts payable | $1,400 |
| Jan 25, sell 60 at $25 | Accounts receivable | Sales revenue | $1,500 |
| Jan 25, cost of that sale | Cost of goods sold | Inventory | $720 |
| Jan 31, count finds 2 units missing | Cost of goods sold | Inventory | $24 |
- The $1,240 on January 15 is 100 units at $10 plus 20 units at $12.
- The $720 on January 25 is 60 units at $12, what is left of the second layer.
- On January 31 the records show 120 units, 20 at $12 and 100 at $14. The count finds 118. We cost the 2 missing units from the oldest layer, as FIFO would for a sale: 2 × $12 = $24.
Which cost method are you allowed to use?
Under IAS 2, the international inventory standard, you may use FIFO or weighted average, and LIFO is not allowed. In the United States LIFO is allowed, with a tax condition attached.
Paragraph 25 of IAS 2 says the cost of inventories “shall be assigned by using the first-in, first-out (FIFO) or weighted average cost formula”. Items that are not ordinarily interchangeable are costed by specific identification under paragraph 23.
The IASB’s Basis for Conclusions records that the Board “decided to eliminate the allowed alternative of using the LIFO method” (BC9), because of LIFO’s “lack of representational faithfulness of inventory flows” (BC19).
Australia, New Zealand and India carry the same paragraph 25 in AASB 102, NZ IAS 2 and Ind AS 2. The IFRS Foundation’s profile for the Philippines says the country has adopted IFRS Accounting Standards as PFRSs, with a list of exceptions that does not include IAS 2.
In the United States, LIFO is an accepted practice. The SEC staff’s guidance on LIFO inventory practices speaks of “acceptable LIFO accounting practice”, and IRS Publication 538 explains how to adopt LIFO with Form 970.
The condition is in 26 U.S.C. § 472(c). To use LIFO for tax, the reports you give owners and lenders for the first LIFO year must use the same LIFO procedure.
Section 472(e) applies the same test in later years. The IASB noted this kind of tax link in BC20 and called it “an issue for local taxation authorities”.
| Method | IAS 2 (IFRS) | United States |
|---|---|---|
| FIFO | Allowed | Allowed |
| Weighted average | Allowed | Not listed in IRS Publication 538 |
| LIFO | Not allowed | Allowed, with the § 472(c) condition |
Publication 538 lists specific identification, FIFO and LIFO as ways to identify cost and does not list average cost, so ask your tax adviser before assuming either way.
What do FIFO, LIFO and average cost give on the same numbers?
They give three different cost-of-goods-sold figures from identical purchases, and only FIFO gives the same answer under both inventory systems.
We ran the example from the previous section through each method. Opening stock is 100 units at $10, 100 units arrive at $12 on January 10 and 100 at $14 on January 20. We sell 120 units on January 15 and 60 on January 25, 180 units for $4,500 of revenue. The January 31 count is left out here.
| Method | Sale 1 | Sale 2 | Cost of sales | Ending stock |
|---|---|---|---|---|
| FIFO | $1,240 | $720 | $1,960 | $1,640 |
| Moving average | $1,320 | $760 | $2,080 | $1,520 |
| LIFO | $1,400 | $840 | $2,240 | $1,360 |
| Method | Perpetual | Periodic | Gap |
|---|---|---|---|
| FIFO | $1,960 | $1,960 | $0 |
| Average cost | $2,080 | $2,160 | $80 |
| LIFO | $2,240 | $2,360 | $120 |
- FIFO: sale 1 is 100 × $10 + 20 × $12 = $1,240. Sale 2 is 60 × $12 = $720.
- Moving average: after the January 10 purchase, 200 units cost $2,200, or $11.00 each, so sale 1 is 120 × $11.00 = $1,320. After January 20, the 80 units left ($880) plus 100 units at $14 make 180 units costing $2,280, or about $12.67 each, so sale 2 is 60 × $2,280 ÷ 180 = $760.
- LIFO: sale 1 takes the newest layer first, 100 × $12 + 20 × $10 = $1,400. Sale 2 takes the January 20 layer, 60 × $14 = $840.
- Periodic: the method is applied once to the whole month. Average cost is $3,600 ÷ 300 units = $12.00, so 180 × $12.00 = $2,160. LIFO takes the newest costs, 100 × $14 + 80 × $12 = $2,360. FIFO takes the oldest, 100 × $10 + 80 × $12 = $1,960.
On $4,500 of revenue, perpetual gross profit runs from $2,540 with FIFO to $2,260 with LIFO. Prices rose during the month, which is why LIFO shows the higher cost. IRS Publication 538 says that in rising prices “LIFO will produce a larger cost of goods sold and a lower closing inventory”.
The gap between the two systems exists because a perpetual system fixes the cost at each sale from the stock on hand that day. A periodic system applies the method once to the whole month’s purchases, so a later purchase can be treated as sold earlier.
Our Inventory Value Calculator takes all the purchases first and then the total units sold, so it gives the periodic result. Entering these three purchases with 180 units sold returns $1,960 for FIFO and $2,360 for LIFO, the periodic figures in the table above.
How does perpetual differ from periodic?
The difference is when the cost of a sale is recorded: at each sale in a perpetual system, once at period end in a periodic one. OpenStax describes the periodic system as one that “updates the inventory balances at the end of the reporting period”.
| Perpetual | Periodic | |
|---|---|---|
| Cost of a sale recorded | At each sale | At period end |
| Entries per sale | Two: revenue and cost | One: revenue |
| Inventory account | Current after every transaction | Current only after the period-end adjustment |
| Cost method applied | At each sale, to stock on hand | Once, to the period’s purchases |
| Physical count used for | Checking records and booking shrinkage | Finding ending stock and cost of sales |
Why does a perpetual system still need physical counts?
Records drift from the shelf through theft, damage, miscounts and missed scans, so counts correct them.
IRS Publication 538 is direct: “You must take a physical inventory at reasonable intervals and the book amount for inventory must be adjusted to agree with the actual inventory.”
Auditing guidance says the same from the other side. PCAOB AS 2510, paragraph .10, describes “well-kept perpetual inventory records” that “are checked by the client periodically by comparisons with physical counts”.
A full count of every item once a year is not the only route. Paragraph .11 recognises controls, including statistical sampling, that are “sufficiently reliable to make unnecessary an annual physical count of each item of inventory”, provided the auditor is satisfied the results would be substantially the same.
The January 31 line in the example is what a count produces: the shelf is two units short, so cost of sales rises by $24.
What does a perpetual inventory system require?
It needs a record for every item, the actual cost of every receipt, a way to capture each movement, one consistent cost method, and regular counts.
- An item record with quantity and cost. Publication 538 says “Inventory accounts must be charged with the actual cost of goods purchased or produced and credited with the value of goods used, transferred, or sold.”
- Capture at the point of movement, usually barcode or RFID scans at receiving and at the till.
- One cost method, applied consistently. IAS 2 requires “the same cost formula for all inventories having a similar nature and use”, and Publication 538 says “Your inventory practices must be consistent from year to year.”
- Counts, and a rule for booking the difference, as in the January 31 entry above.
What are the benefits and limits?
The benefit is a current view of stock and cost of sales. The limit is that the view is only as good as the data entered.
- Benefit: cost of sales and stock value are available at any time, not only after a period-end count.
- Benefit: reorder points can be checked against stock on hand every day.
- Benefit: AS 2510 paragraph .11 recognises that reliable controls, including sampling, can make a full annual count unnecessary.
- Limit: a missed scan or a wrong unit of measure moves the record away from the shelf until a count catches it.
- Limit: it does not remove counting, as the IRS and PCAOB text above shows.
- Limit: under moving average and LIFO, cost depends on the order entries are posted, which is why the perpetual and periodic figures differ in the example.
Which software supports a perpetual system?
Choose software by the cost methods it offers, because some offer methods your standard does not allow.
Inventory management software does the record-keeping, and the cost methods on offer vary by product. We read three vendors’ own documentation on 29 October 2026.
| Product | Cost methods |
|---|---|
| QuickBooks Online | FIFO or Moving Average Cost, fixed once chosen |
| Dynamics 365 Business Central | FIFO, LIFO, Average, Standard and Specific |
| Zoho Inventory | FIFO or weighted average (moving average) |
Business Central’s documentation describes LIFO as “Disallowed in many countries/regions”. Check your standard before you select a method a package offers.
FAQs
What are the types of perpetual inventory systems?
A perpetual system is not divided into FIFO, LIFO and average types. Those are cost methods, a separate choice that sets what each sale costs, and IAS 2 does not allow LIFO. Perpetual systems differ in how records are captured, from manual stock cards to software with barcode or RFID scanning.
What should you decide first?
- Reporting under IFRS or a national version of it: choose FIFO or weighted average, and confirm your software offers one of them.
- Filing in the United States and weighing LIFO: settle section 472(c) with your accountant first, because the reports you give owners and lenders must use the same procedure.
- Either way: set a count routine and book the differences.
Run FIFO or LIFO on your own purchases with our online Inventory Value Calculator
Standards, IRS and SEC guidance, and vendor pages were read on 29 October 2026. The figures in the example tables are our calculation from the numbers shown.
Using Google Search? Add erp-information.com as a preferred source.